A $475,000 Arizona home was sold for about $8,000 after an alleged $977 homeowners association debt, showing how small bills can still cost people everything.
Story Snapshot
- The HOA foreclosure began after a reported $977 delinquency and ended in an $8,172 sale back to the association.
- Court reporting says fees and legal costs later pushed the tab into the thousands before the sale.
- Arizona raised the foreclosure trigger in 2025 to 18 months or $10,000 owed for planned communities.
- The case highlights how late fees and attorney costs can turn small debts into home-loss risks.
What Happened In Mesa
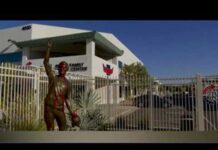
Reports say Mesa homeowner Toby Newton fell behind on quarterly homeowners association assessments of about $170. Coverage states the association started foreclosure after the balance was about $977, and the property later sold back to the association for $8,172. A separate outlet put the home’s market value near $450,000 to $475,000, sharpening concern about proportionality between the debt and the loss of equity. Newton told a television outlet he asked for a payment plan but was denied.
Court-focused reporting in Chinese language media cites filings that show the debt grew during the case. By July 2025, the ledger reportedly listed $1,311 in unpaid assessments and late charges, about $1,042 in costs, and $3,345 in attorney fees, totaling roughly $6,579 before the sale. That pattern fits a common cycle. Small delinquencies can snowball as late fees, collection charges, and legal work stack onto the lien before a judge orders foreclosure.
Why Arizona Law Allowed This Before 2025
Arizona lawmakers changed the rules in 2025 for planned communities after years of lower thresholds. A legislative fact sheet says the new law bars foreclosure unless the owner is at least 18 months delinquent or owes $10,000 or more, whichever comes first. Before that date, guides describe a lower trigger. Many associations could foreclose after one year of delinquency or $1,200 in unpaid assessments, excluding late fees and attorney fees from the dollar test.
Those older limits made “small debt, big equity loss” cases possible when owners missed notices or could not catch up in time. Lawyers say associations still had to meet notice rules and file in court, but they could pursue foreclosure once the legal threshold was met. The Mesa timeline in coverage shows foreclosure steps starting in late 2024 and a court order in mid‑2025, which would have placed the case under the earlier, lower standard rather than the new 2025 protections.
Why This Strikes A Nerve Across The Spectrum
Homeowners who work hard to build equity see a process where a missed bill can take a house. Many say the system seems built for speed and fees, not second chances. People on the right view this as local rule by boards and lawyers who face little pushback. People on the left see a wealth gap story, where a paper debt erases years of savings. Both sides doubt that anyone in power is looking out for regular families caught in legal gears.
Mesa couple fights to keep home after HOA foreclosure https://t.co/M849hbeD3F via @YouTube
— Melanie🇺🇲 (@mefbama) September 16, 2026
This case also shows a gap between reform and reality. Lawmakers raised the bar in 2025, but that does not help owners whose cases began earlier. Reports say Newton offered to make payments but could not stop the legal clock once costs mounted. Arizona’s court and legal guides tell owners to read every notice and respond fast, but that is hard when illness or job loss hits. The system remains lawful, yet many ask if it is still fair.
What To Watch Next
Policy watchers should track whether Arizona extends the higher foreclosure threshold to condominiums and clarifies how fees count. Some legal summaries say the dollar test excludes attorney fees and late charges under older rules, which matters when balances grow. Wider adoption of long grace periods, mandatory payment-plan offers, and clearer notice could reduce shock outcomes. Until then, owners should document all payments, request ledgers, and get help early to avoid fee spirals.
Sources:
foxnews.com, nypost.com, justicecourts.maricopa.gov, azcourthelp.org, worldjournal.com, azhoawatch.org, chdblaw.com, goodlaw.legal
© nationalusnews.com 2026. All rights reserved.